Buying a Condo in Pompano Beach: How to Compare HOA Fees, Assessments and Total Monthly Costs
A lower asking price does not necessarily mean a more affordable condo. Higher association dues, insurance expenses or assessment payments can outweigh the mortgage savings on a cheaper unit. When buying a condo in Pompano Beach, compare the purchase price, ongoing expenses and cash required before deciding which property fits your budget.
Use this guide alongside Pompano Beach condos for sale. The goal is a comparison grounded in each building’s documents, rather than assumptions about what a condo should cost.
Build a Complete Monthly Ownership Budget
The cost of owning a condo in Pompano Beach extends beyond the mortgage payment. Include:
- Mortgage principal and interest: Use your lender’s terms, including mortgage insurance when applicable.
- Estimated post-purchase property taxes: Divide the estimated annual bill by 12.
- Association dues: Include condominium, master-association and any other mandatory recurring charges.
- Unit-owner insurance: Obtain a property-specific HO-6 quote and review deductibles and coverage gaps.
- Applicable flood coverage: Have an insurance professional evaluate association coverage, unit coverage and lender requirements.
- Utilities and services: Include electricity, internet, water and other expenses excluded from dues.
- Interior maintenance: Budget for appliances, air conditioning and other owner responsibilities.
- Assessment obligations: Record installment amounts and end dates separately from ordinary dues.
Avoid double counting. If dues include water, do not add a second water allowance. If your mortgage payment includes tax and insurance escrows, separate those components before adding them again. Association reserve contributions already included in dues should not be added twice; a personal allowance for interior repairs serves a different purpose.
Two Hypothetical Condos: The Cheaper Purchase Costs More Monthly
Every amount below is illustrative, not a local average or current quote. Both purchases assume 20% down and a fully amortizing, 30-year fixed mortgage at an illustrative 6.5% annual interest rate, without mortgage insurance. Principal and interest are rounded to the nearest dollar. Taxes and insurance are invented budgeting amounts, not percentage-based estimates or coverage recommendations.
| Item | Condo A | Condo B |
|---|---|---|
| Purchase price | $350,000 | $425,000 |
| Down payment: 20% | $70,000 | $85,000 |
| Mortgage amount | $280,000 | $340,000 |
| Monthly principal and interest | $1,770 | $2,149 |
| Estimated taxes per month | $500 | $625 |
| Association dues per month | $1,200 | $650 |
| HO-6 insurance per month | $150 | $150 |
| Additional unit flood coverage allowance per month | $50 | $50 |
| Utilities excluded from dues per month | $175 | $175 |
| Personal interior maintenance allowance per month | $100 | $100 |
| Monthly budget before assessment | $3,945 | $3,899 |
| Temporary assessment installment | $300 for 36 months | $0 assumed |
| Monthly budget during assessment | $4,245 | $3,899 |
Condo A costs $75,000 less to purchase but requires $346 more monthly during the assumed assessment period. Without that assessment, its monthly budget is still $46 higher. The illustration assumes comparable included services; actual comparisons require adjusting for differences.
Upfront cash is separate. Condo B requires $15,000 more down. Both buyers also need closing costs, prepaids, applicable association charges and any required reserves. Condo A’s remaining assessment totals $10,800. This example assumes the buyer may continue installments, the lender accepts that arrangement and the contract assigns them to the buyer. If payment is required at closing, move the obligation to upfront cash rather than counting it twice.
This compares budgeted cash flow, not investment returns. Mortgage principal builds equity; appreciation, selling expenses and opportunity cost are outside the example. Dues, taxes and premiums can change, and the absence of a current assessment does not guarantee none will arise.
Compare Association Fees by What They Fund
Pompano Beach condo HOA fees are commonly used as shorthand for condominium association dues. Compare the actual budget: building insurance, management, staffing, landscaping, elevators, pools, utilities and reserve contributions. Identify any separate recreation, parking or master-association charges.
Low dues alone do not establish value. Determine whether the budget supports required maintenance and reserve funding. Higher dues may cover substantial services, but they can also reflect expensive operations. Read the budget alongside financial statements, reserve balances and planned projects.
Ask what changed between the current and proposed budgets. Insurance renewal dates, expiring service contracts and repair schedules can reveal expenses that the current monthly figure does not yet capture.
Pompano Beach Condo Buyer Checklist: Documents to Review
- Finances: Current and proposed budgets, latest available annual financial statements, interim financial reports, reserve balances, owner delinquencies and association debt.
- Building condition: Applicable milestone inspections, structural integrity reserve studies, engineering reports, repair scopes, permits and evidence of completed work.
- Assessments: Adopted notices, payment schedules, remaining balances and proposed projects discussed in meeting minutes.
- Insurance: Master-policy information, flood coverage where applicable, limits, deductibles, exclusions and renewal information.
- Governance: Declaration, bylaws, amendments, rules and recent board and membership meeting minutes.
- Legal matters: Pending litigation, material claims, code issues and notices requiring professional evaluation.
- Use restrictions: Rental waiting periods, lease limits, pet rules, occupancy requirements and renovation restrictions.
- Practical approvals: Parking rights, storage, application requirements, approval timelines, deposits and move-in procedures.
Florida’s DBPR inspection resources explain milestone inspections and structural integrity reserve studies. Applicability depends on the building and governing requirements. A reserve study addresses future funding; it does not replace inspection findings or prove that recommended work is complete.
Our Florida condo SIRS article provides additional background. Have an attorney evaluate document-delivery rights and contract deadlines under the applicable transaction and Florida condominium disclosure law.
Have Your Lender Review the Building Early
Borrower preapproval does not establish condominium project eligibility. A lender must also determine whether the property satisfies the requirements of the selected loan program. Building condition, insurance, finances, litigation and assessments can affect that decision.
Fannie Mae’s project requirements, for example, address unresolved critical repairs and related special assessments. Paying an assessment does not itself prove the underlying repair has been completed. Submit building information early and obtain the lender’s requirements before relying on a financing scenario.
There is no universal condo down payment. Requirements vary by program, occupancy, borrower and project. Cash buyers still need building due diligence because future buyers’ financing options can affect resale.
Estimate Your Taxes and Insurance Independently
A seller’s tax bill may reflect exemptions and accumulated assessment limitations that do not carry over to your ownership. Your eligibility for homestead benefits or portability requires separate evaluation. Review the Broward County Property Appraiser’s guidance and new-homebuyer tax estimator; use the property-record estimator for a specific unit. Estimates are not guaranteed future bills.
Similarly, association insurance does not eliminate the need to evaluate individual coverage. Have an insurance professional reconcile the master policy with your HO-6 policy, personal belongings, interior improvements, liability and loss-assessment coverage. Ordinary maintenance assessments are not automatically insured losses. Evaluate flood coverage separately, including association limits and any unit-level needs.
Oceanfront Versus Inland: Compare the Actual Buildings
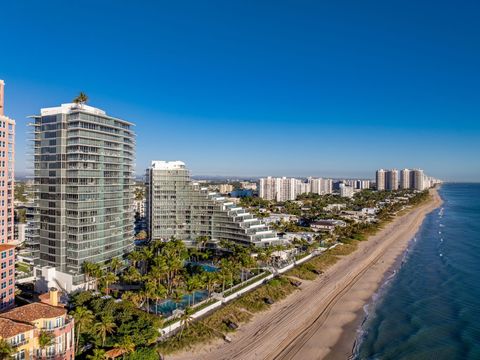
When reviewing Pompano Beach oceanfront condos for sale, examine documented exterior maintenance, waterproofing, balconies and applicable coastal infrastructure. For inland properties, review drainage, roofs, elevators and other relevant systems with the same discipline.
Location alone does not establish condition, flood exposure or future assessments. Compare elevation, mapped flood information, construction, maintenance history, insurance and professional findings. Neither an oceanfront address nor an inland location substitutes for building-specific evidence.
A Simple Condo Comparison Worksheet
| Comparison item | Condo 1 | Condo 2 |
|---|---|---|
| Price, down payment and loan terms | ________ | ________ |
| Monthly mortgage, taxes and insurance | ________ | ________ |
| Dues, included services and extra charges | ________ | ________ |
| Utilities and personal maintenance allowance | ________ | ________ |
| Assessment balance, installment and end date | ________ | ________ |
| Total monthly budget / total upfront cash | ________ | ________ |
| Reserve funding, repairs and unresolved questions | ________ | ________ |
| Lender review and insurance quote status | ________ | ________ |
Use comparable sales, unit condition, documented building obligations and ownership costs to inform an offer. A credit can reduce upfront cash without resolving recurring costs or project eligibility. Distinguish verified obligations from estimates and unanswered questions.
Frequently Asked Questions
Are lower condo dues always better?
No. Compare included services, reserve funding and maintenance obligations before judging value.
Who pays an existing special assessment?
Responsibility depends on the contract, assessment terms and applicable law. Obtain written confirmation of balances and allocation before closing.
Does mortgage preapproval cover the building?
No. Ask your lender to confirm project eligibility for your specific loan.
Can I use the seller’s taxes in my budget?
Use an independent post-purchase estimate. The seller’s exemptions and assessment history may produce a misleading comparison.
Can dues increase after I buy?
Yes. Review proposed budgets and planned projects, and allow room for changing expenses.
Local Guidance for Comparing Condo Purchases
Pompano Beach Realty is a local resource for comparing properties, obtaining relevant information and coordinating with lenders, inspectors, insurance professionals and attorneys. Buyer-representation compensation depends on the applicable agreements.
Pompano Beach Realty
Oliver Hoffmann, Broker
1591 E Atlantic Blvd
Pompano Beach, FL 33060
Phone: 954-505-6000
www.PompanoBeachRealty.com
Pompano Beach Oceanfront Condos For Sale